

Hey, you are reading Investment Talk. If you’d like to join the 20.5k other readers learning about life, the stock market, and the companies within it, subscribe below. You can check out my other articles and follow me on Twitter too. If you enjoy today’s article, feel free to share it, it helps a lot. Now let’s begin.
What’s on Dimon’s Mind?
Taken a few days ago, does this look like a banker stressed about the collapse of the US economy?

The letters from the CEOs of the companies that make up the world’s financial infrastructure make for interesting reading. Banks, payment rails and credit card companies may be complicated to understand, but the commentary dispersed throughout their shareholder letters and earnings calls provide exquisite insight into the economy, the market, and the health of the nation’s financial plumbing. These rare individuals have a front-row seat on the SS.USA (and other nation-bearing vessels). Who better than Jamie Dimon, the CEO of America’s largest bank, to extract perspective from?
Here are ten takeaways from his most recent1 annual letter.

1. From a virtuous cycle to a vicious one
From a savings glut to scarce capital; Dimon expressed concerns we may be enduring a once-in-a-generation sea change from the virtuous cycle we have enjoyed since the GFC to the vicious cycle that looms ahead. He notes this is further complicated by the tensions of war; which are leading to “the rethinking of many economic alliances, as well as trade and national security”.

2. Preparing for economic extremes
The current environment is removed from the typical economic oscillation that JP Morgan tends to ignore. The economic extremes we have faced of late may not be over. While the economy has proven to be resilient, “managing risks is far more than simply meeting the Fed’s annual stress test”.

3. This time may be different
He actually said those four magic words. Well, he actually expressed it in seven; “it may not be true this time”. By ‘it’ he is referring to the inverted yield curve, an eight for eight2 recession indicator, telling us we are due a recession. He claims it's possible this inversion is driven by prior quantitative easing.

He continues to express that the Fed may be forced to increase rates higher than people expect, despite the banking crisis, if inflation persists. “Also, QT may have ongoing impacts that might, over time, be another force, pushing longer-term rates higher than currently envisioned. This may occur even if we have a mild, or not-so-mild, recession, as we saw in the 1970s and 1980s”.
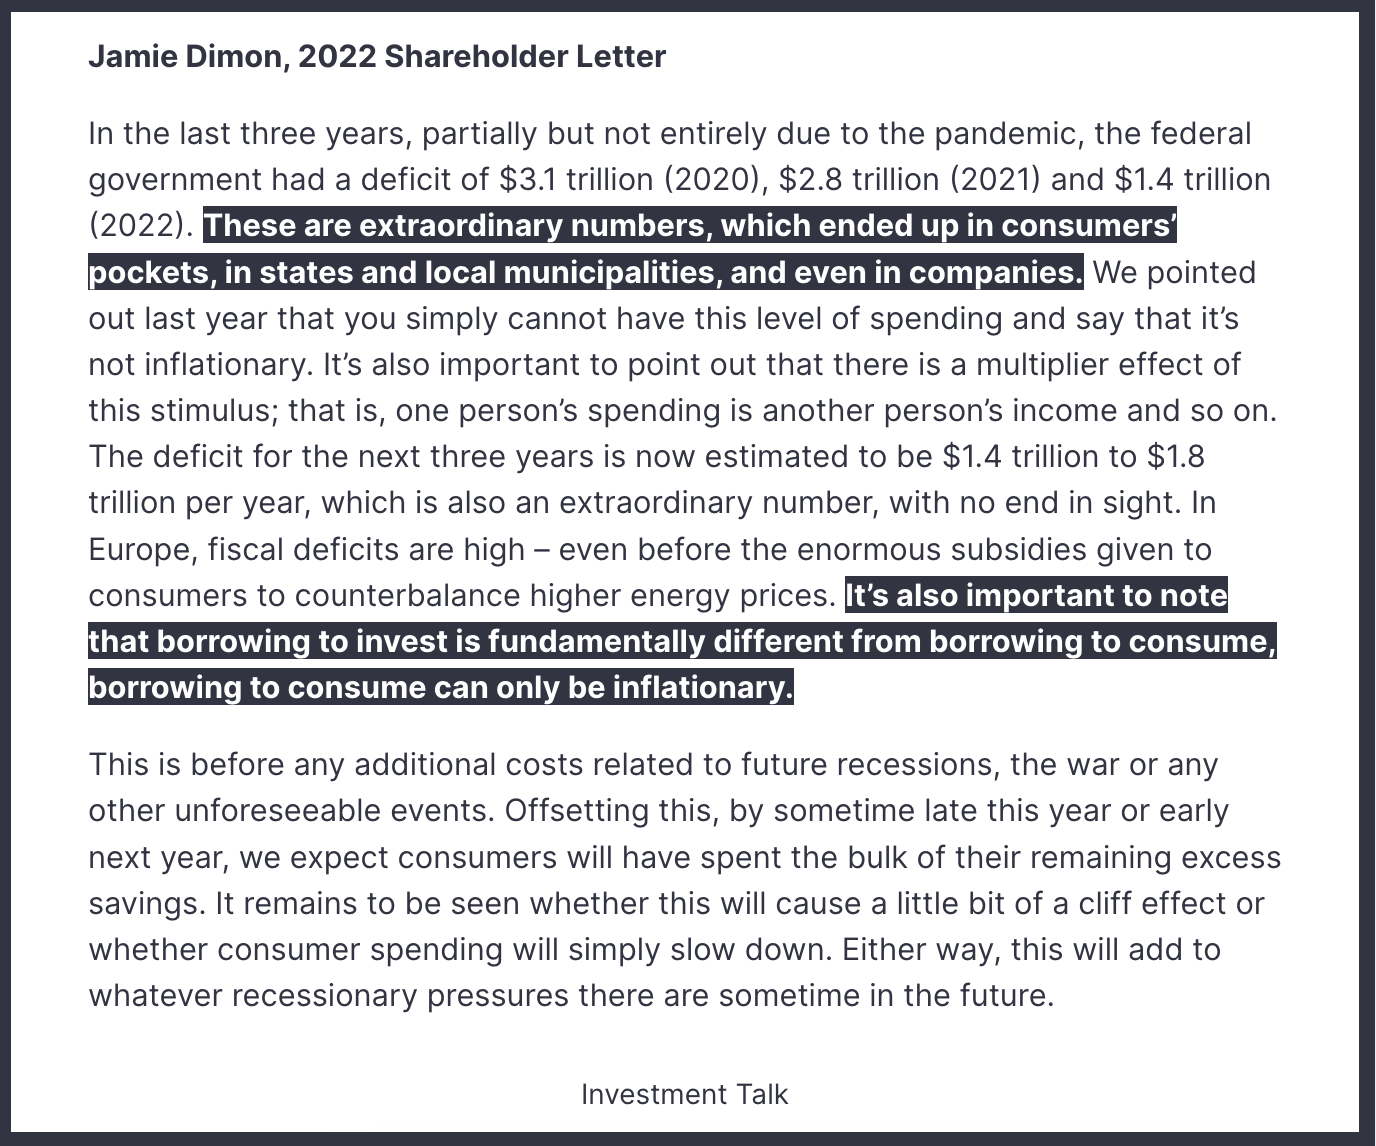
4. Borrowing to consume
Here Dimon explains how borrowing to consume is, by nature, inflationary. The gradual erosion of excess savings may be a source of reprieve, in terms of inflationary spending, but the other edge of this sword is that it will enhance any recessionary pressures that may be ahead.
5. This is not 2008
The collapse of SVB and Credit Suisse significantly altered the market’s expectations. Prior to this, the market was performing “adequately”. As consumer balance sheets appear robust, and unemployment (which recently fell 10bps to 3.5%) remains low, the consumer is in a better place to weather a crisis than they were in 2008.

While the current crisis exposed weaknesses in the system, “it should not be considered, as I pointed out, anything like what we experienced in 2008”. The “unique and complication issues” that the US faces today, as Dimon believes, can be found in the below table.

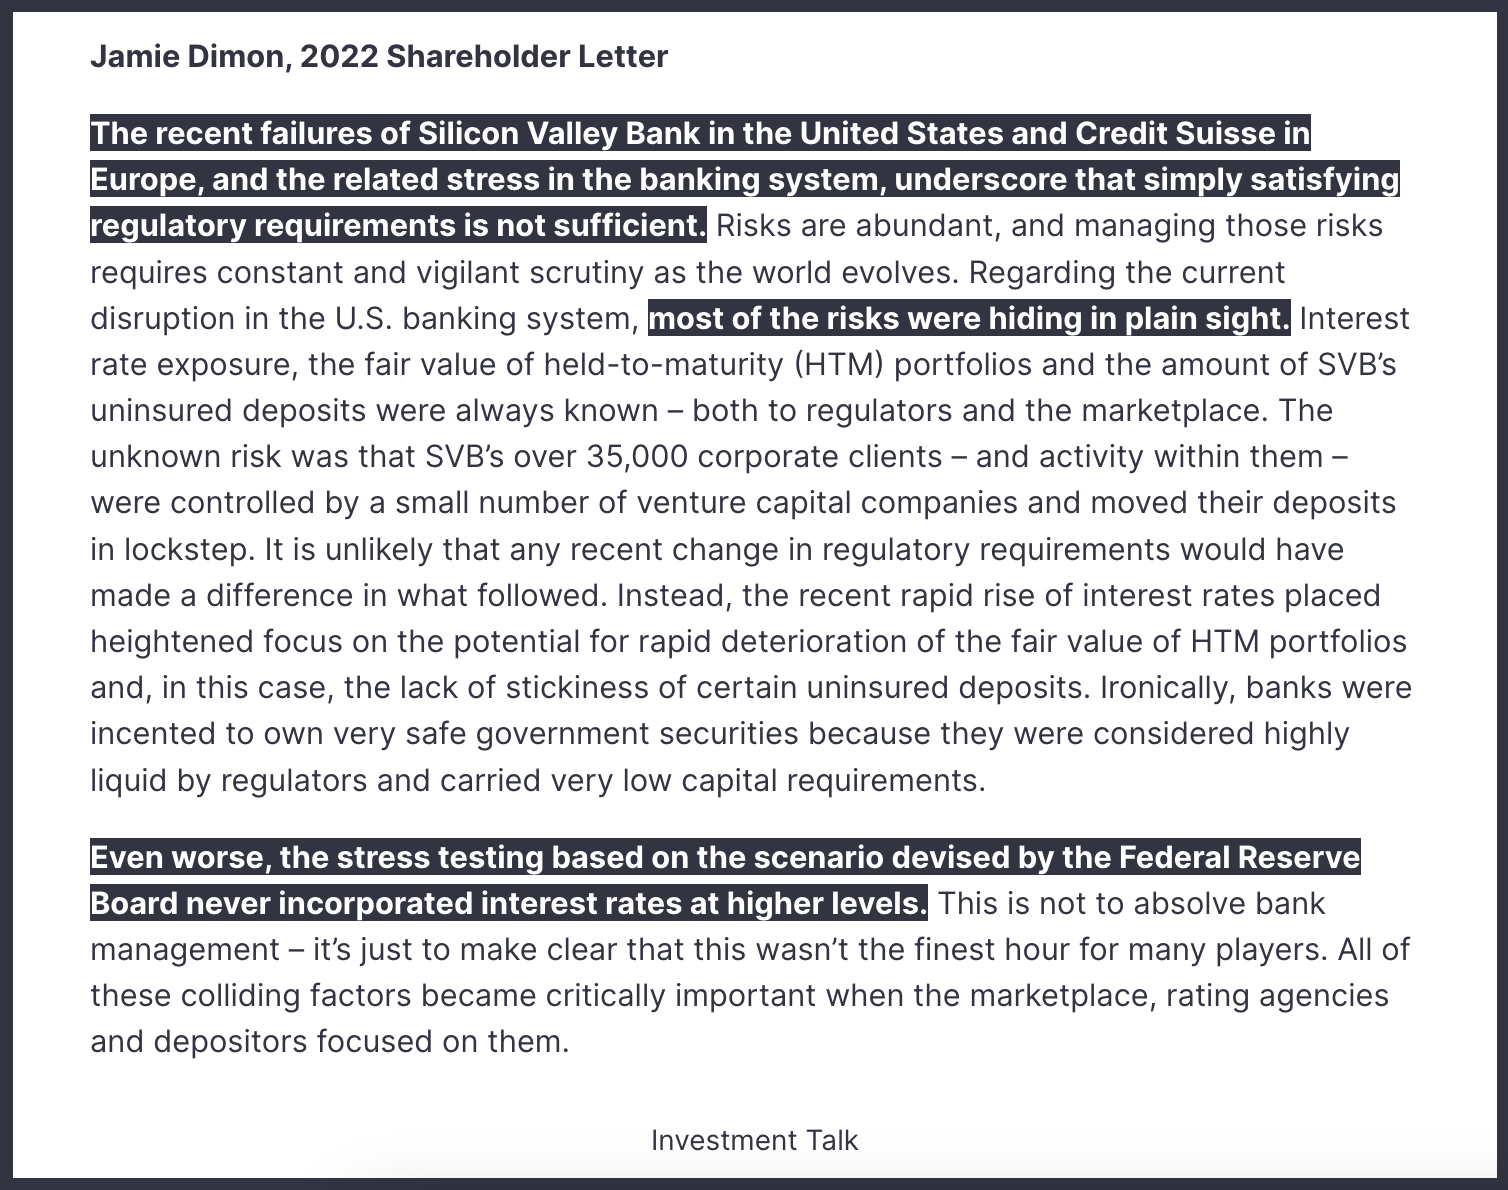
6. The risks of SVB were hiding in plain sight
The failings of SVB will result in changes to the regulatory system, but Dimon urges policymakers to avoid “knee-jerk, whack-a-mole or politically motivated” responses that may do more harm than good. Many of these failings were hiding in plain sight, according to Dimon; demonstrating that simply adhering to regulation parameters is not enough.
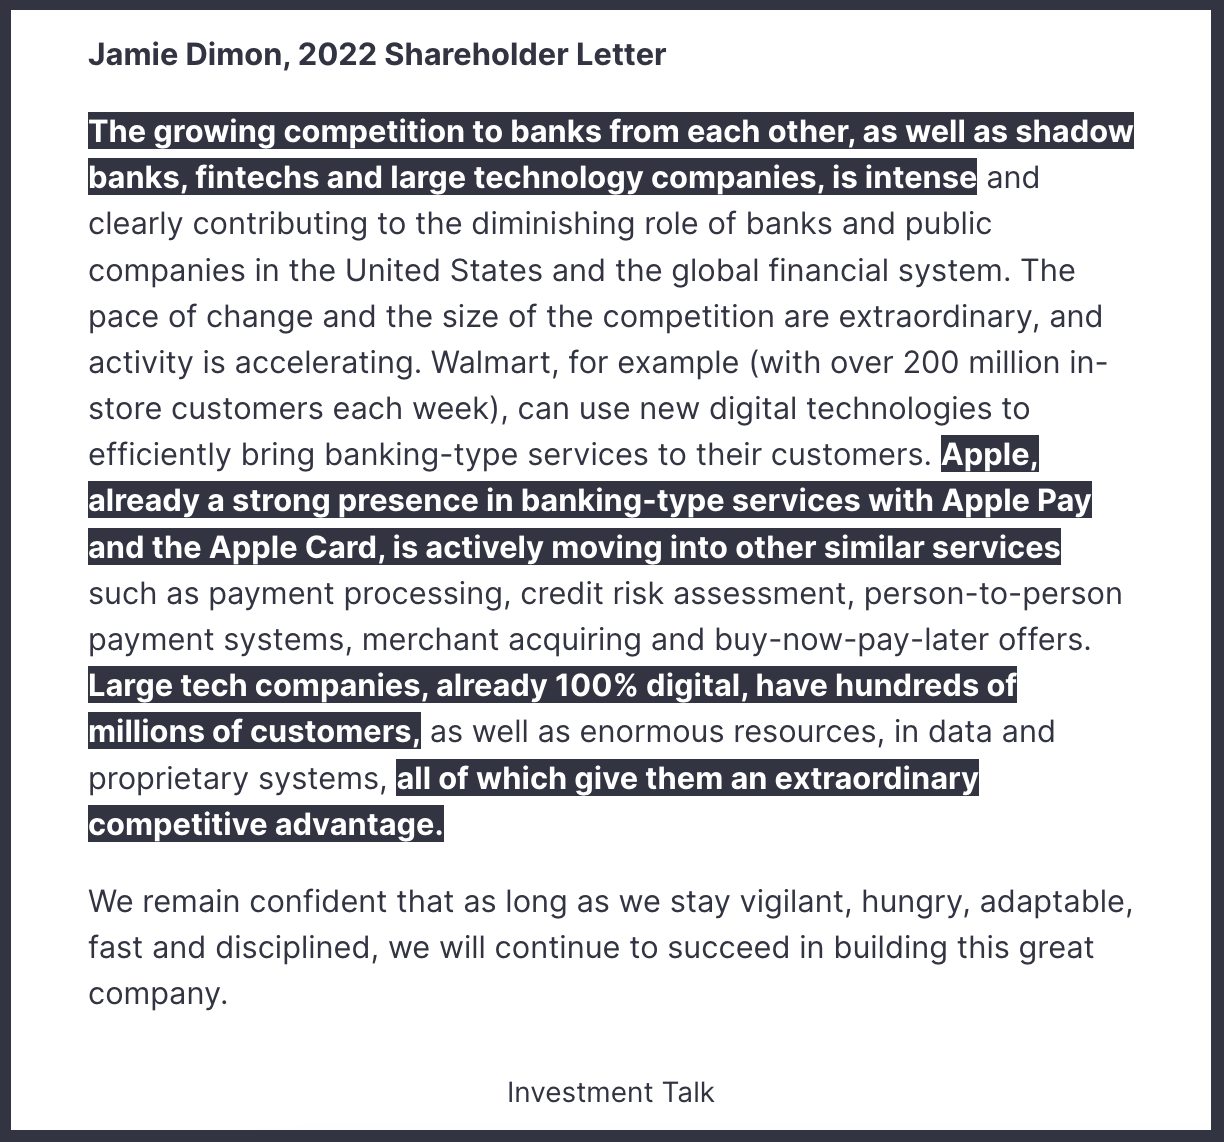
7. Keeping an eye on competitors
A call out for the likes of Walmart and Apple who, with their hundreds of millions of customers, have the resources and systems to carry out services for their consumers that were historically conducted by banks. Companies like them are becoming an increasingly prickly thorn in the side of the consumer division of banks like JP Morgan.
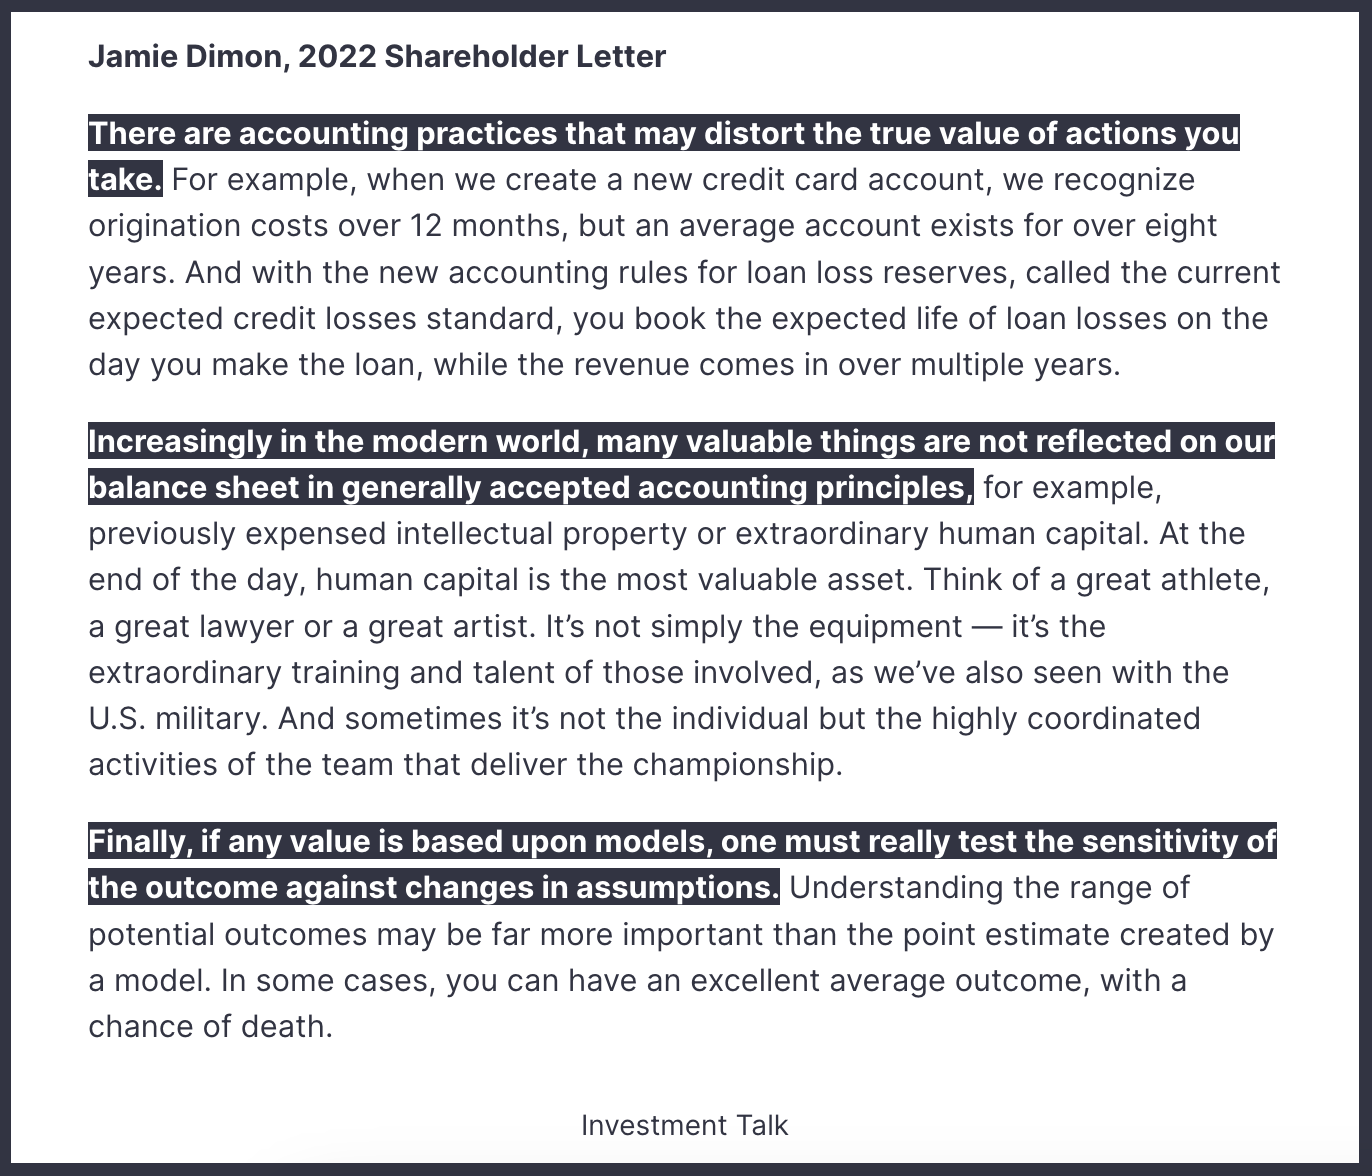
8. Accounting distortion & understanding outcomes
A really great line about managing the sensitivity of outcomes against changes in outcomes; “In some cases, you can have an excellent average outcome, with a chance of death”. This may or may not be a nod to the banking failures we have seen in 2023. There were folks who flagged these issues well before the broader market latched onto them, but for the most part, it felt as though everyone that ought not to be, was asleep at the wheel.
9. AI is a focus for JPM
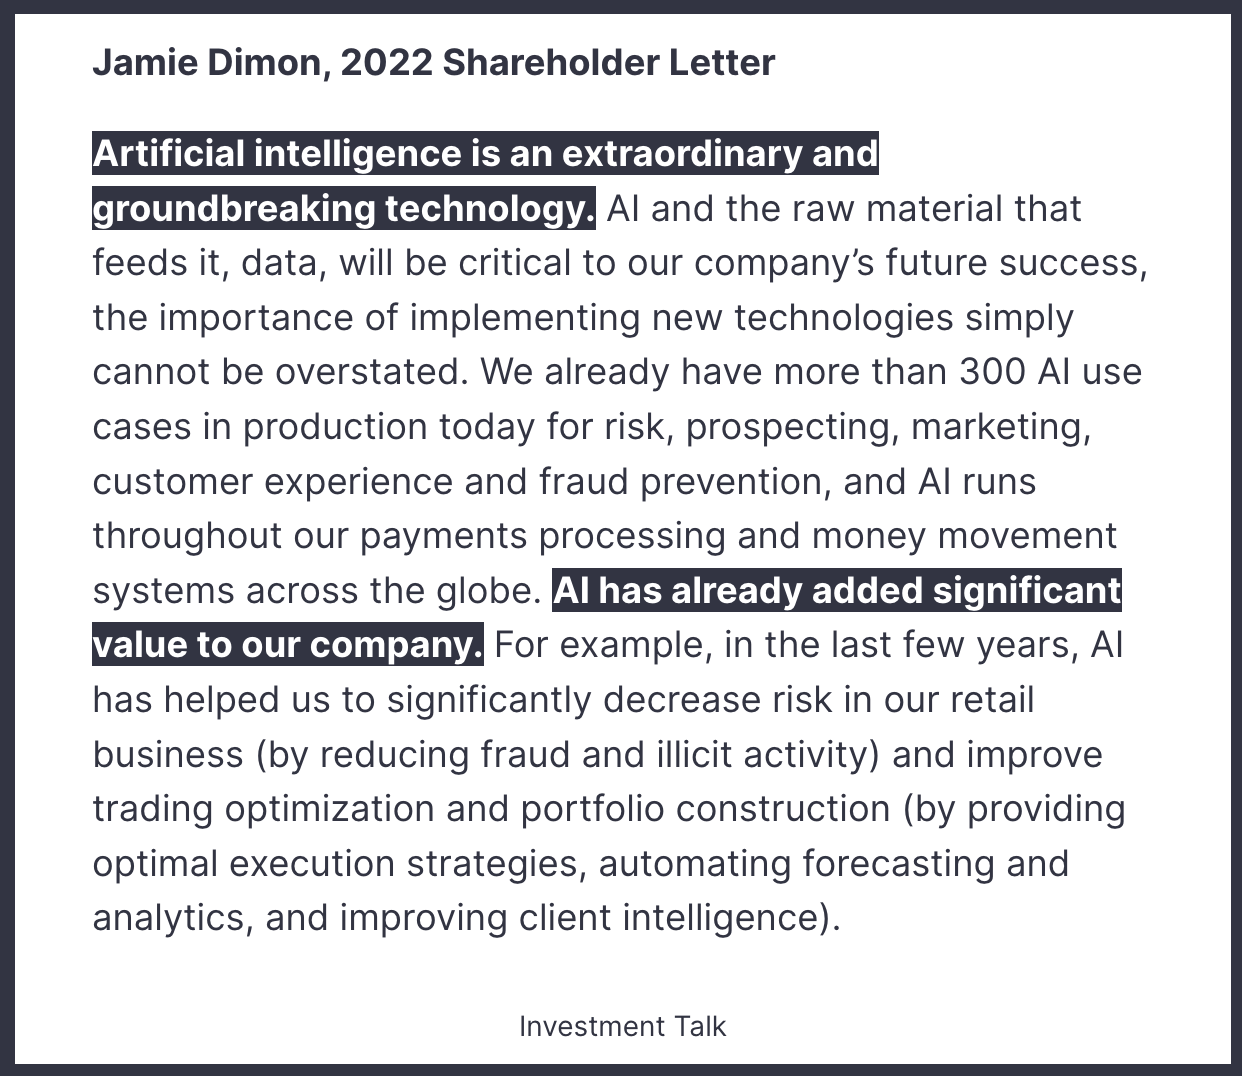
Dimon suggests that AI has “already added significant value to [the] company”. JP Morgan already has more than 2,700 working directly on AI across data management, data scientists, machine learning experts, and research groups.
10. The rise of private equity
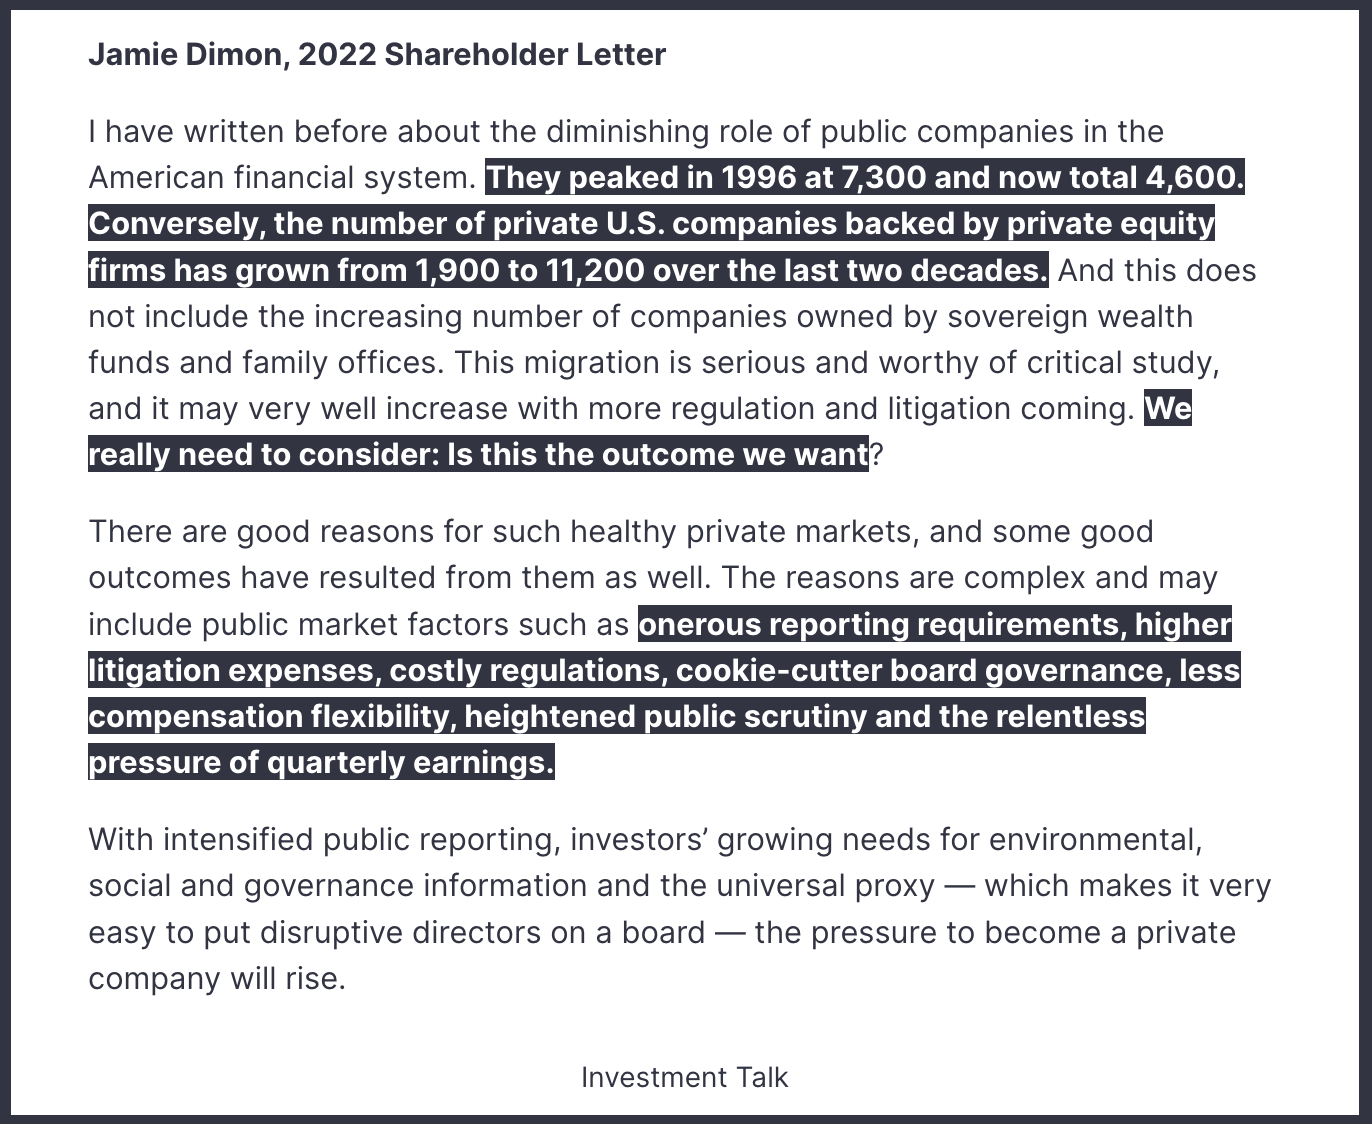
The number of private companies backed by PE firms in the US has grown by almost 500% in the last two decades; incentivised by the absence of various pressures, costs, and limitations to flexibility that being a public entity entails. As it looks like this trend is set to continue, Dimon asks if this is something the US wants to continue incentivising.
Thanks for reading,
Conor
The asterisk here is the pandemic. Before the outbreak of covid, the yield curve had inverted, but we will never know what would have unfolded had it not been for the pandemic.
Nice recap. Point 10 reminds me of a podcast I was listening to recently (Hidden Forces Episode 243 w Russell Napier - paywalled) where the guest makes the point that, with US governments need to fund itself we're likely to see regulation steer money away from particular areas of the economy and into US treasuries in a form of credit rationing, i.e. expensive credit for xyz purpose but cheap credit for the US gov. One area he thinks credit will be steered away from is any industry that is in the business of levering up existing streams of cash flow as opposed to creating to new ones, and private equity will be at the top of the list. So, to Dimon's point, this guests prediction is that indeed the US will NOT continue incentivizing PE. On the other hand, you might guess that industries such as renewable energy, electric vehicles, and domestic chip making factories will continue to get access to cheap credit, and those might be fertile industries to hunt for longs.
Thanks!
I wonder, what is the rationale behind saying the inversion in the yield curve may be linked to prior QE instead of an aniticipated recession? That people have got so used to QE that they don't believe QT is for real and that soon the Fed will start buying Treasuries again, driving the yield on them lower? That that's the new game of the Fed and they will soon be at it again, irrespective of a hard landing or not?