The year is still young so I might be tempting fate here, but I think one of the things 2024 will be remembered for, good or bad, is the year Bitcoin ETFs became mainstream. Regular readers will know I don’t have strong opinions on Bitcoin. I am not an evangelist, I am not a critic. Merely an observer. Don’t expect frequent commentary on the matter from me.
In January 2024, the SEC approved several spot Bitcoin ETFs across familiar issuers such as Blackrock, Ark, WisdomTree, Franklin Templeton, Fidelity, Invesco, and VanEck. Many felt this was the alternative asset classes’ coming-of-age moment. No longer the awkward teenager, Bitcoin had officially arrived on Wall Street. So far, the largest benefactor amongst issuers has been Blackrock.

Blackrock’s IBIT fund quickly became the top dog for fund flows. In less than a quarter, the fund has accumulated more than $16 billion in assets under management. This marks a significant lead over the next-largest funds such as Fidelity’s FBTC ($8.9 billion), Ark’s ARKB ($2.8 billion), Bitwise’s BITB ($2 billion), and VanEck’s HODL ($550 million). Blackrock has grown so fast that it has shattered records; reaching $10 billion in AUM in just 7 weeks. The previous record belonged to SPDR’s Gold Shares ETF (GLD), which took 27 months to cross the $10 billion threshold.

This meteoric rise in the adoption of spot Bitcoin ETFs coincided with a new all-time high for the underlying. Bitcoin recently surpassed $73,000 per unit for the first time; marking the asset’s fourth historic peak following the highs of $19,450 in 2017, $63,400 in April 2021, and $67,700 in November 2021.
Why funds and why now?
A natural question is why would anyone want to acquire exposure to Bitcoin through a fund instead of directly owning it via a brokerage like Coinbase? Buying Bitcoin directly gives an investor direct ownership and discretion over storage, security, and usage. It also provides transparency (you know exactly how much you own), purity (you are not purchasing a derivative of the asset you want to own), and discretion over what market price you purchase the asset. Funds, on the other hand, offer a different solution. One relates to the dilemma of storage, as explained in the prospectus for Blackrock’s IBIT fund:
“Traditional forms of investing directly in Bitcoin require deciding where to store the purchased bitcoin, which can be in a crypto wallet or on a crypto exchange. This approach gives the investor certain direct responsibilities in preventing security risks such as theft or loss of private keys, which are essentially passcodes to a crypto wallet. With a bitcoin ETF, investors own shares of the ETF, removing the need to determine where to store their bitcoin, as this is handled by the ETF's custodian”.
In some instances, funds may reduce the burden of high trading costs as well as complexities surrounding tax reporting. For some, the convenience of acquiring exposure to Bitcoin via the same brokerage that you purchase stocks in is enough to warrant an appeal (eliminating the need to use an alternative brokerage like Coinbase). Ultimately, it depends on the buyer. Crypto-savvy individual investors may not see the appeal of the fund vehicle. What's more, there are circles within the Bitcoin community that exhibit distrust towards government and regulatory bodies. The idea of investing alongside the Patagonia-wearing nimrods won’t appeal to those folks.
For professionals and advisors, the added layer of regulation and oversight associated with funds provides security and legitimacy; as opposed to the somewhat lesser-regulated field of crypto exchanges. Institutions may also favour ETFs because they align with their investment mandates and compliance requirements. Direct investment in Bitcoin might not fit the risk profile or regulatory constraints that institutional investors adhere to. Before the launch of these spot ETFs, institutions or clients of advisors had fewer choices. They could directly purchase the asset; which we discussed may not be a viable approach in some cases. They could purchase Bitcoin futures. Before Grayscale (GBTC) converted to a spot ETF, it existed as a closed-end Bitcoin trust; allowing investors to gain exposure to Bitcoin price movements. Other options included crypto-adjacent or related stocks, private equity, or venture. The new spot ETFs offer a more accessible, smoother, and generally lower-cost, entry into the market.
While spot Bitcoin ETFs currently offer exposure to a single asset (Bitcoin) it’s conceivable to imagine a future where these funds offer exposure to a varied selection of crypto assets. This diversification, plus the familiarity of funds, and the relative ease of access, may broaden the appeal further.
It’s not much safer
Choosing a fund over direct ownership offers a solution to the storage dilemma. Wallets connected to the internet (“hot wallets”) are convenient but susceptible to hacks or malware. Similarly, holding your assets on an exchange means they are prone to breaches and theft. Offline wallets that utilise hardware (“cold wallets”) offer more security than hot wallets concerning breaches, but can just as easily be lost, stolen, or damaged. If this happens, you may be able to recover the asset with private keys or seed phrases. Lose both, and you have little recourse.
Funds offer a solution to the storage dilemma but don’t resolve it. The individual merely passes on the responsibility to the custodian. Just because your Bitcoin exposure is derived from a fund, you are not exempt from the risk of permanent capital loss. Similar to cases of individual folly, if a custodian somehow loses access to the private key required to access Bitcoin, whether by destruction or misplacement, those Bitcoins are irreplaceable. They are non-restorable. Gone. For shareholders, this implies that if the Bitcoin Custodian loses access to the Bitcoin, the shareholders could potentially face a total loss of their investment associated with that Bitcoin.
Going back to Blackrock’s IBIT prospectus, some of these concerns are addressed. I’ll try to summarise it in a few sentences. If BlackRock, through its Bitcoin Custodian, were to irretrievably lose access to the private keys necessary to access the Bitcoin, then the Bitcoin would effectively be lost, and shareholders could potentially lose their entire investment associated with that Bitcoin. In the event of a theft or a security breach where Bitcoin is stolen, Coinbase, which is the parent company of the Bitcoin Custodian, has a commercial crime insurance policy that covers such events. If such a security breach occurs and Bitcoin is stolen, the insurance policy could provide coverage for the loss, subject to the terms and limits of the policy. It's important to note that this insurance is shared among all of Coinbase’s customers, is not specific to the fund, and may not be sufficient to cover all losses. Hardly reassuring.
I would hazard a guess that the likelihood of a custodian losing access to the asset is considerably lower than that of an individual. However, and this is an obvious statement, the consequences of the former would be considerably more devastating to a larger body of investors.
Where are the casualties?
Blackrock has undeniably been the biggest success story in this saga; as young as it may be. Individual investors with direct ownership in Bitcoin have no doubt benefited from the recent surge too. But so often in financial markets, when one theme is doing well, it comes at the expense of something else.
In this case, Grayscale’s GBTC is a notable example. Having been the only game in town for some time, the birth of new spot ETFs has shaken the market. Armed with greater choice, investors have flocked to the newer and more cost-effective funds at the expense of Grayscale. Since the beginning of this year, each of the new spot ETFs has seen positive inflows; all bar one. GBTC has seen outflows of more than $6 billion, bleeding daily.

The gap in AUM between Blackrock’s IBIT and Grayscale’s GBTC is now ~$10 billion and is expected to narrow as more funds flow from the incumbent to the new funds. Another interesting trend has been the relative flows of Gold and what some call “Digital Gold” (aka Bitcoin). Comparing the cumulative flows since January between Blackrock’s IBIT and the world’s largest Gold ETF, SPDR’s GLD, paints a stark contrast.

Collectively (including the significant outflows from GBTC) these eleven spot Bitcoin ETFs have produced more than $14 billion in inflows YTD. SPDR’s GLD has seen outflows of almost $3 billion.
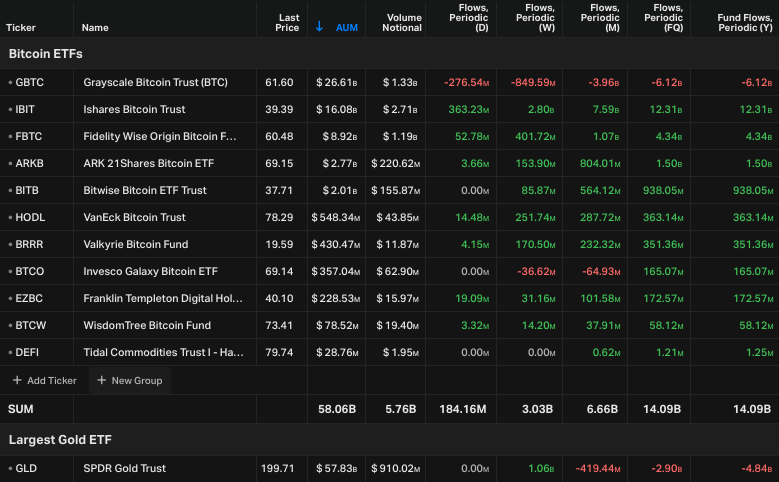
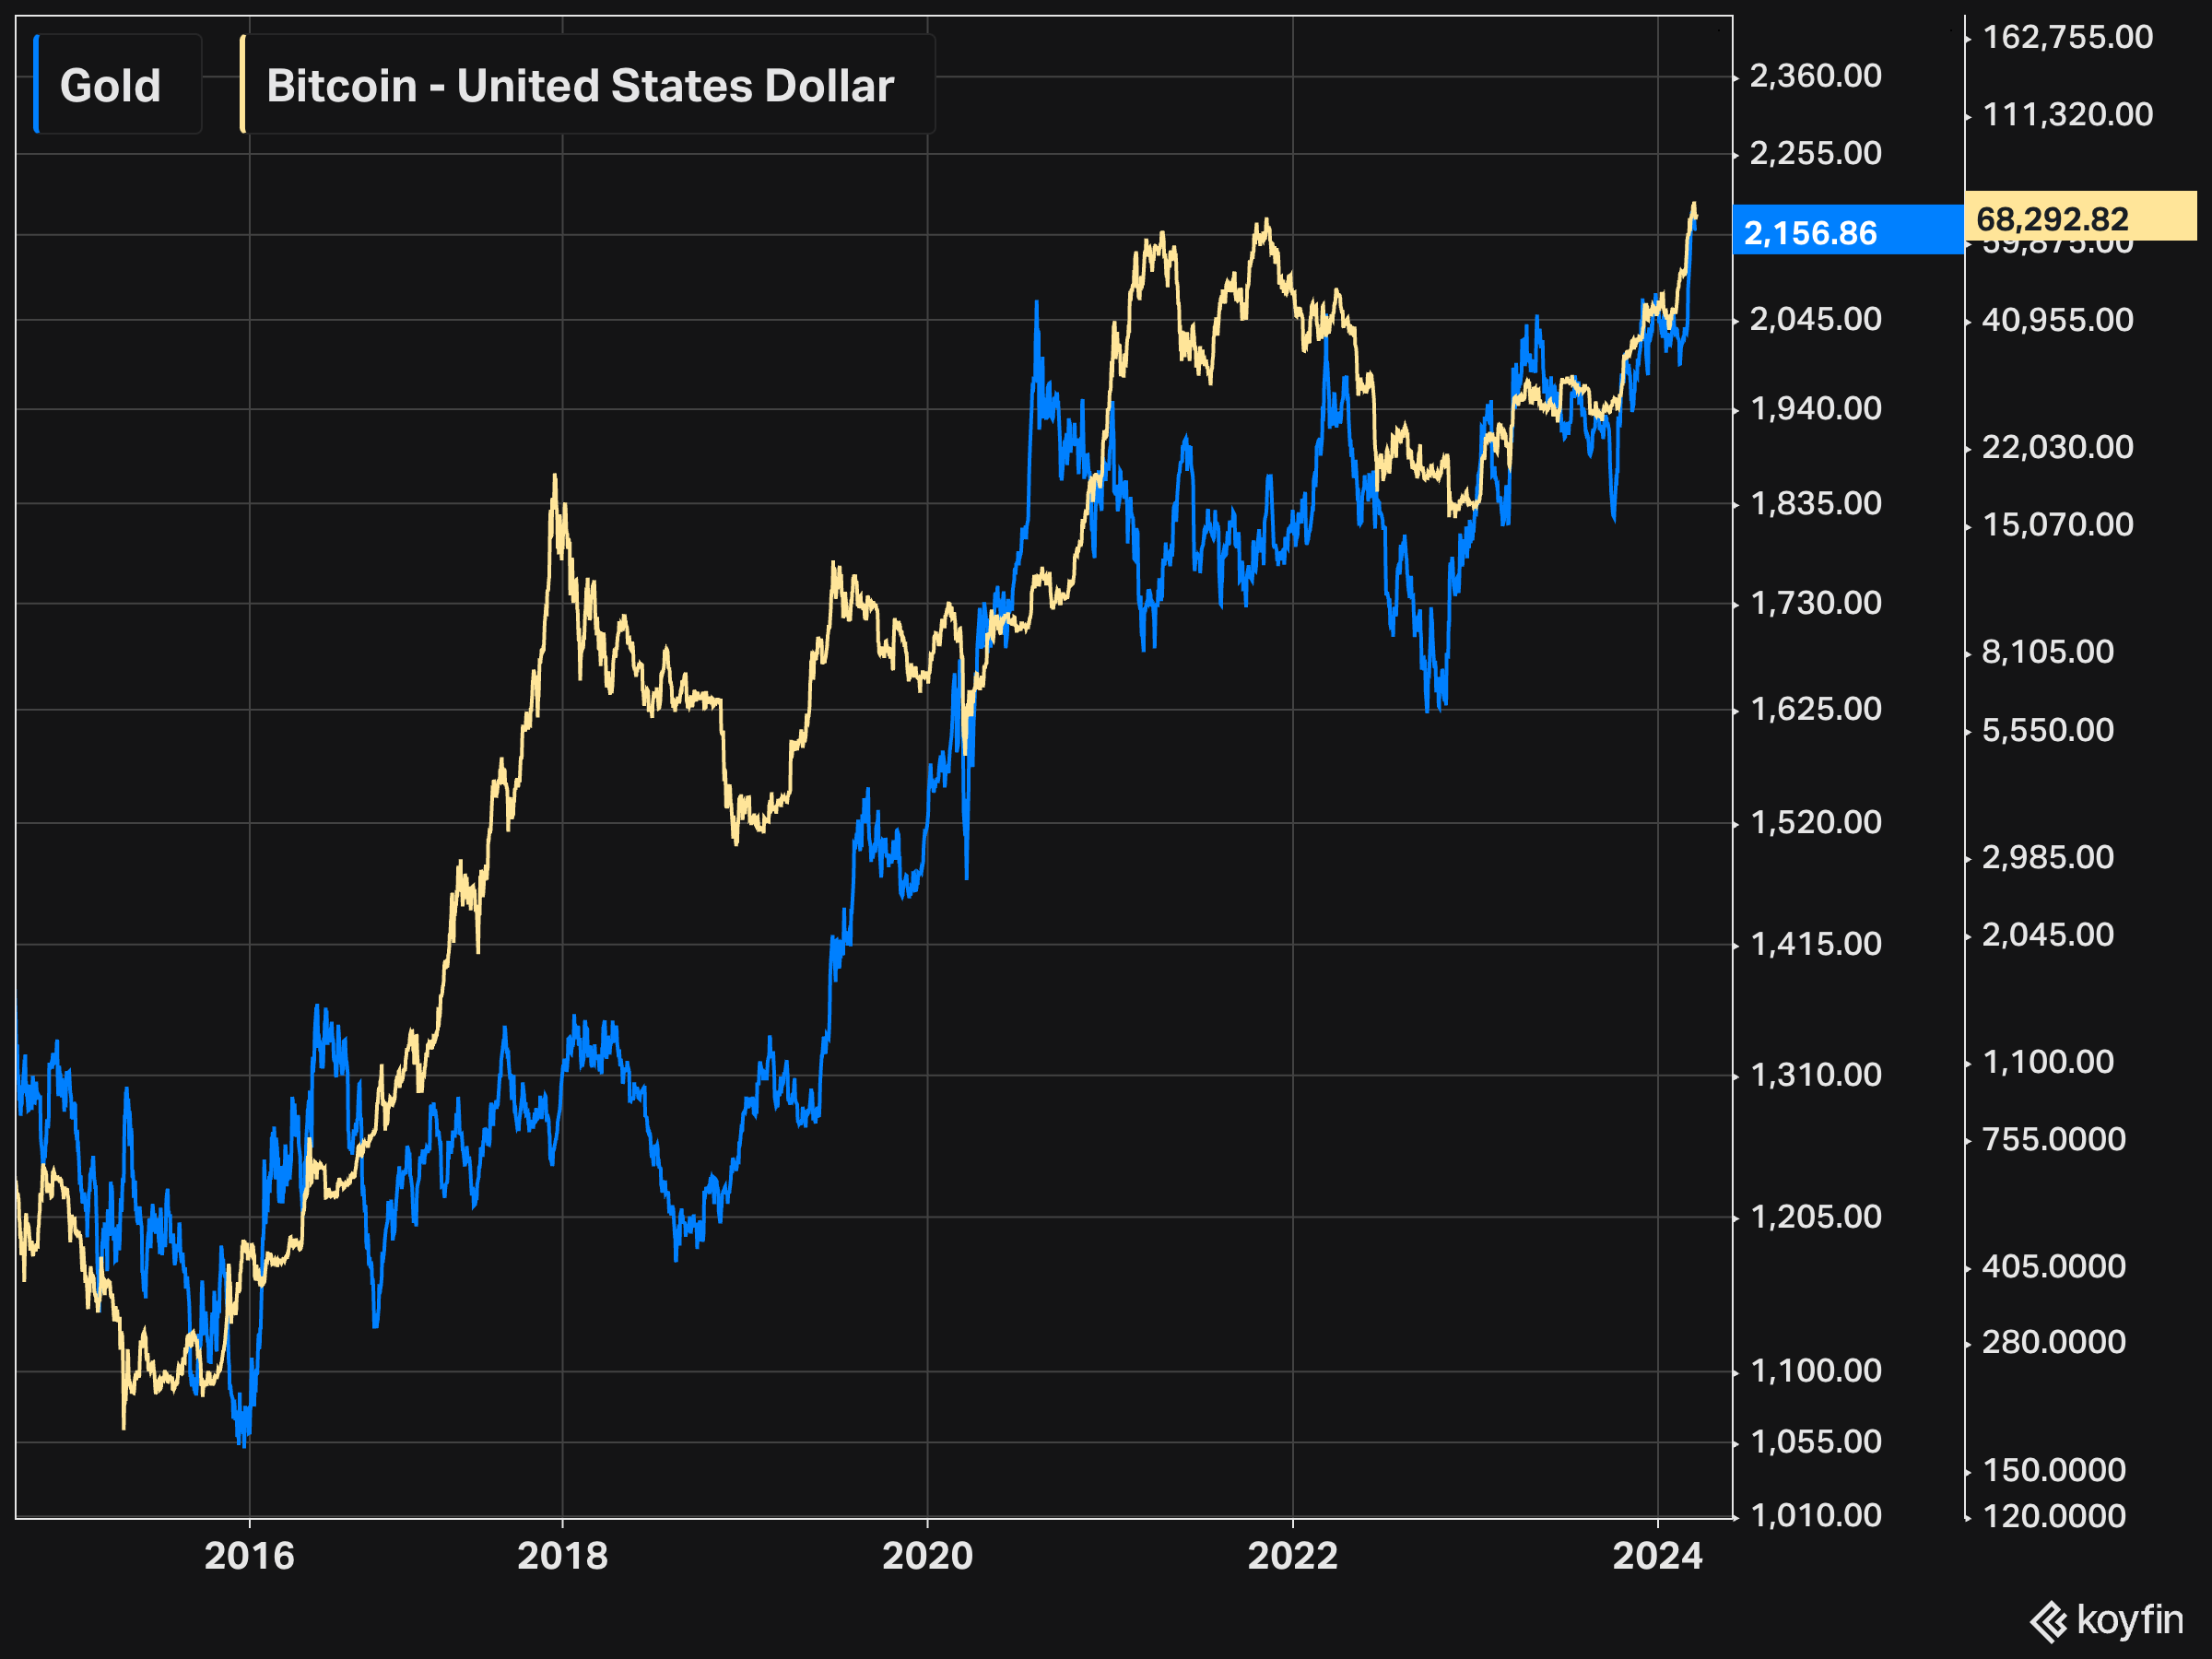
Combine the AUM of these Bitcoin funds and it totals $58.1 billion. In the space of less than 3 months, that figure surpasses the $57.8 billion in AUM held in the world’s largest Gold ETF. Both Bitcoin and Gold have recently made new highs1. It’s hard to say if this trend will persist, but it’s certainly a sign of the times which we inhabit currently.
Adoption
The real “winner” in all of this is Bitcoin through furthered adoption. In recent Bitcoin cycles (I am sure you have all noticed) a spike in price momentum for Bitcoin often comes with the byproduct of greater speculative behaviour in adjacencies. In 2021 we saw the birth of the NFT craze. Images of monkeys selling for millions of Dollars. Gurus claiming that mortgages will soon be processed via the blockchain. Marketplaces like OpenSea saw their valuations soar. At the outset of 2023, OpenSea’s valuation was once an astonishing $15 billion. The most recent data suggests it’s now valued at closer to $1 billion (about $1 billion too high if you ask me). The NFT sensation was brief; and quickly decapitated as markets soured and speculators came to their senses.
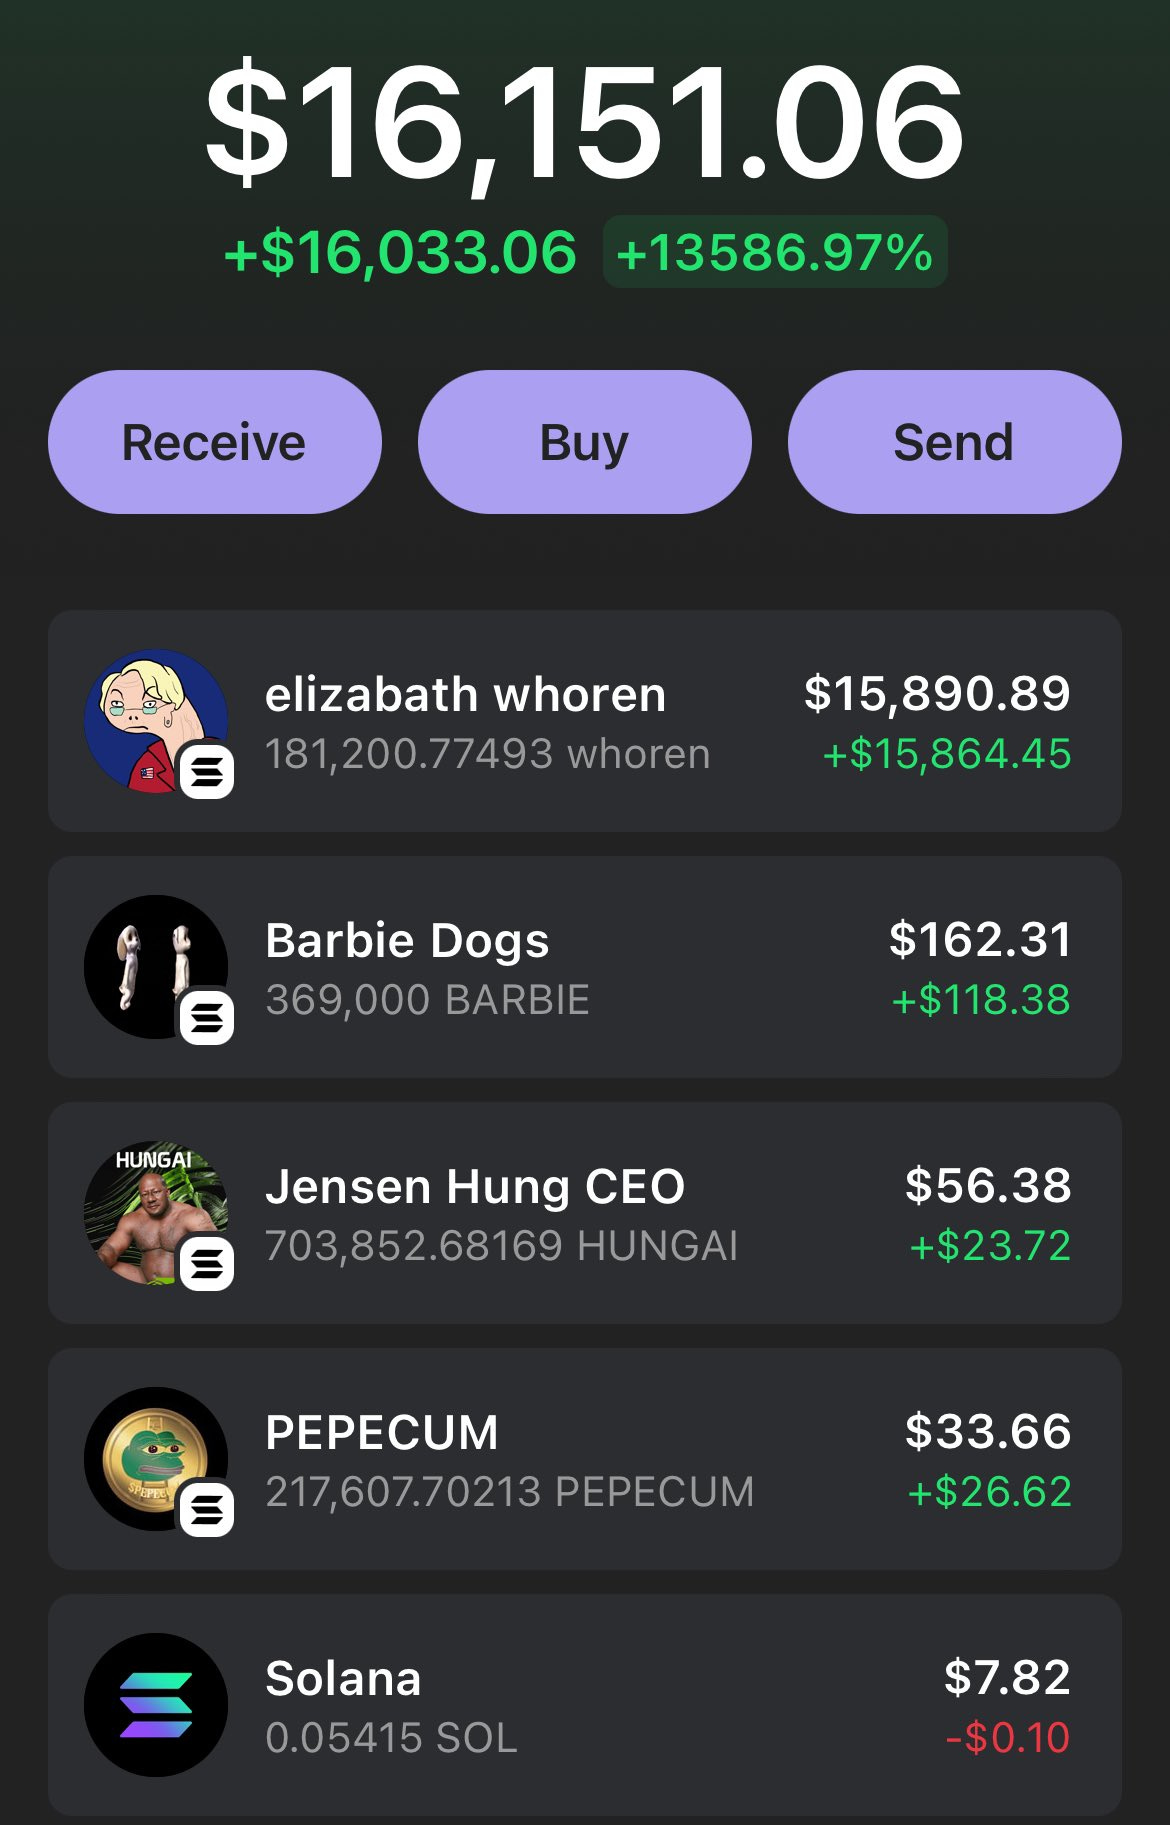
This time around, a new wave of crypto bots and altcoins are slapping the pavement. In what must be the most remarkable case of investor amnesia to date, just two years following the last cycle, investors are once again gobbling up “assets” like Joe Boden or Elizabath Whoren2. This activity is being aided and abetted by custodians such as Coinbase who handily provide detailed instructions on how to trade these meme-assets.

I am reasonably confident that while gains may be made in the short-term trading assets of the meme variety, over the long term they are bound for zero. The rise of broad speculation which often coincides with a Bitcoin run may be unfortunate or misleading for the asset class; through means of association. Alternatively, it could be a fairly obvious signal that Bitcoin remains just that; a speculative asset with few alternative means. Without getting too deep in the weeds, while I am not an advocate of Bitcoin, I can appreciate its likeness to Gold.
I don’t hold a strong view of either Gold or Bitcoin; I just intended to share the data I am observing. I’ll leave the postulation and pontification up to you, the reader.
Thanks for reading,
Conor
Gold and Bitcoin prices as of 18th March 2024.
Screenshot taken from Twitter.